
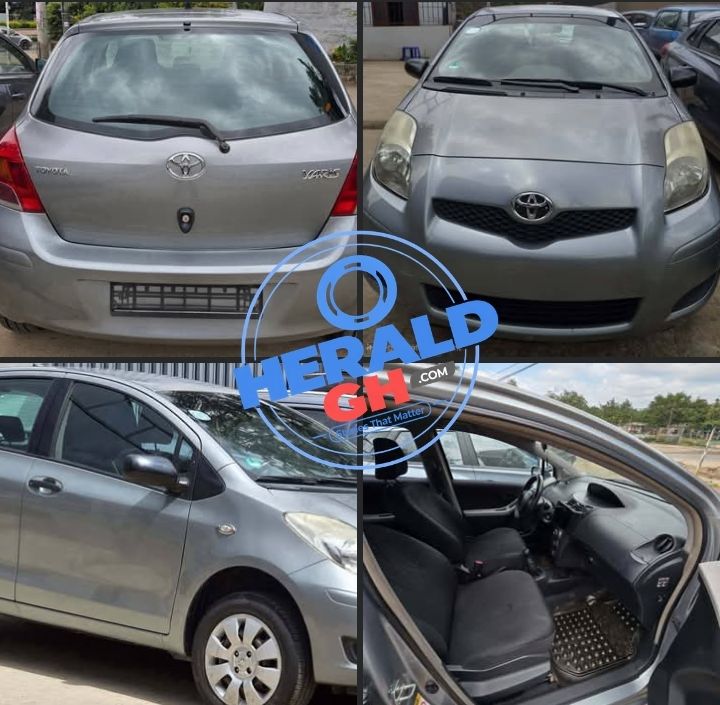
What is “work and pay” in Ghana?
Work and pay in Ghana refers to a scheme where individuals acquire vehicles through structured programs allowing them to earn income while gradually paying for the vehicle. An arrange I entered into months ago which is the reason I write this article to share my experience in this article.
Work, Pay and the Promise of Ownership
There was a time when the phrase “work and pay” sounded like an opportunity but many individuals and companies are now asking questions if this arrangement is beneficial to both partners. Many young Ghanaians between the ages of 20-30 want only meaningful source but lack the necessary funds to start a transport business so many ends up with this agreement;
You get a vehicle, work with it, make agreed payments, and after several years, the vehicle becomes yours. For a young Ghanaian without enough money to buy a car outright, it sounds almost perfect. You don’t need to have the full purchase price sitting in your bank account. Instead, you put down a deposit, take possession of the vehicle, work with it and gradually pay the balance. The dream is simple:
Work today. Pay gradually. Own tomorrow.
But what happens when tomorrow never comes? What happens when someone has paid 70%, 80% or even 85% of the agreed amount and the vehicle is taken away? What happens to the deposit? What happens to all the money already paid? What happens when the driver has spent money repairing a vehicle that technically still belongs to someone else? And perhaps the biggest question:
At what point does a legitimate financing arrangement become unfair or exploitative?
These questions deserve serious attention as work-and-pay arrangements continue to attract people seeking opportunities in Ghana’s transport sector. While work and pay maybe something meaningful to both partners involve there is always the good, bad and ugly that needs to be talked about.
My experience
On April 17, a cousin posted work and pay electric vehicle (ranging 205km) with daily sale of GH¢ 350 for 29 months and a deposit of GH¢ 3,000 in our family group. The deal looks good after several month of searching for a car as another source of income in addition to what i was doing. I did my calculation as any person will do. I went into the agreement hoping for a positive turn around but after four days into the agreement and I realize its not something that will help me so i worked a week thinking to recover my deposit before returning it, but I was rather running into debt.
The Good: A Door into Business
Let’s be fair from the beginning, work and pay is not automatically a scam, in fact, it can be an excellent business opportunity. Imagine a young man called Kofi. Kofi has a driving license and several years of driving experience.
He wants to enter the ride-hailing business, but he doesn’t have enough capital to purchase a vehicle. A vehicle owner offers him a car under a work-and-pay agreement. Kofi pays a deposit. He receives the vehicle.
He registers it for the agreed commercial purpose. Every day or week, he makes a payment, whatever remains after fuel and other expenses is his income. If he completes the agreed payments, ownership is transferred to him. For Kofi, this can be life changing. He has moved from being someone looking for employment to someone building an asset. That is the positive side of work and pay. It can provide:
- Access to a vehicle without paying the entire amount upfront.
- An opportunity to enter the transport business.
- A pathway to vehicle ownership.
- A source of income.
- Valuable business experience.
- An opportunity to build capital for another business.
For someone who has no access to traditional bank financing, such arrangements can open doors. But there is another side.
The Deposit: The First Big Question
Before the vehicle even starts generating money, the driver may be asked to pay a deposit. Let’s imagine a vehicle is valued at GH¢100,000. The owner says:
“Pay GH¢20,000 deposit and take the car.
The driver finds the money, maybe he borrows from family, maybe sells something, maybe takes a loan, and maybe he uses his entire savings. He pays the GH¢20,000 and now the vehicle has been handed over to him. But the driver must understand something very important:
A deposit is not automatically the same thing as ownership.
What does the contract say happens to the deposit if the agreement is terminated? Is it refundable? Is it part of the purchase price? Is it forfeited if the driver defaults? Does the driver receive credit for the deposit toward eventual ownership? What happens if the vehicle is repossessed? These questions should be answered before the money changes hands. A driver who simply hears:
“Pay the deposit and start working”
without understanding the agreement may be putting thousands of cedis at risk.
The Vehicle May Cost More Than You Think
Here is another issue that potential drivers should examine carefully. Suppose a vehicle’s cash value is GH¢100,000, bunder a work-and-pay arrangement, the driver is required to pay:
- GH¢20,000 deposit
- GH¢250 per day
- For several years
The total amount paid could eventually be significantly higher than the vehicle’s cash price. That doesn’t automatically make the arrangement unfair. Financing normally involves additional costs and risk, but the driver should know the total amount payable before signing. Not just:
“GH¢250 per day.” The important question is:
“How much will I have paid when this vehicle finally becomes mine?”
That number can completely change how attractive the deal looks.
GH¢250 a Day Sounds Small
This is where psychology enters the equation. Someone tells you: “It’s only GH¢250 per day.” GH¢250 doesn’t sound enormous when you hear it in isolation. But multiply it.
GH¢250 × 26 working days = GH¢6,500 per month.
Over one year, that becomes GH¢78,000 if paid for 12 months at that rate. And that’s before considering fuel, servicing, repairs, insurance, food, data and other operating expenses. Suddenly the “small” daily payment doesn’t look so small. This is why anyone considering work and pay must stop thinking only in terms of daily payments. Think in terms of:
Total cost.
The Driver Says: “I Have Already Paid 85%”
Now we reach one of the most controversial situations. Imagine Kofi signs an agreement to pay a total of GH¢150,000 for a vehicle. He pays his deposit and works for years. He makes payment after payment and sacrifices weekends and works through rain. He spends money maintaining the vehicle.
Eventually, his records show that he has paid approximately 85% of the agreed amount. He has only 15% left. Then the unfortunate happens, the vehicle breaks down and can’t continue pa the sales while he repairs the vehicle, the driver and owner disagree over who should pay for a major repair. He misses several payment schedules and perhaps there is a dispute over the account. The owner takes back the vehicle. Kofi is devastated.
His argument is simple:
How can I have paid 85% and still lose the car?
The owner’s argument may be equally simple:
You agreed to the payment conditions. You defaulted, so I exercised my rights under the agreement.
And suddenly what looked like a business relationship becomes a legal and financial dispute.
Does Paying 85% Mean the Car Is Yours?
This is where emotions must give way to the contract. Not necessarily. Paying 85% does not automatically mean ownership has legally transferred. The answer depends on what the agreement says, the nature of the financing arrangement and applicable law. If ownership is only transferred after the final payment, the vehicle may remain legally owned by the original owner until the contractual conditions are satisfied. But that does not mean every repossession is automatically fair. There can still be serious questions about:
- Whether the driver was properly notified.
- Whether the owner followed the contract.
- Whether the payment records are accurate.
- Whether the deposit was properly accounted for.
- Whether previous payments are refundable or forfeited.
- Whether the repossession process complied with applicable law.
- Whether the terms themselves were unfair or misleading.
This is why “I have paid 85%” is morally powerful but not, by itself, a complete legal argument, the contract matters.
The Real Nightmare: Losing Everything
Consider a more extreme example.
A driver pays GH¢30,000 deposit and over several years, he pays another GH¢100,000. Total amount paid GH¢130,000. The agreed total payment is GH¢150,000. He has therefore paid about 87%. Then the vehicle is repossessed after a dispute. What happens to the GH¢130,000? Does the driver receive any money back? Does the owner keep everything? Does the driver receive credit for what has already been paid? Does the vehicle get resold? If it is resold, what happens to the proceeds? These are not small questions.
For an ordinary Ghanaian, GH¢130,000 may represent years of savings, sacrifice and debt and this is why work-and-pay contracts should not be treated like casual WhatsApp agreements. They involve serious financial commitments.
The Hidden Cost: Repairs
There is another issue many people overlook. Who pays for repairs? Imagine a driver takes a relatively old vehicle under a work-and-pay arrangement. Three months later, the gearbox develops a major problem. and the repair costs GH¢8,000.
The owner says:
You are the one using the car. Fix it.
The driver responds:
But the car belongs to you.
Who is right?
There is no universal answer and the contract should say. Routine maintenance and wear-and-tear may be treated differently from major mechanical failures, but if the agreement doesn’t clearly state responsibility, the argument can become ugly. And while the two parties argue, the vehicle may remain parked. The driver loses income, the owner loses income and the payment deadline doesn’t necessarily stop. Everyone loses.
The Driver Who Maintains Someone Else’s Asset
This creates an interesting contradiction. A driver may spend thousands of cedis maintaining a vehicle while still not being the legal owner. He may replace tyres, change engine oil, Repair suspension, fix electrical faults, repair the air conditioning, replace worn parts, etc. These expenses help preserve the owner’s asset but the driver may still be required to make his daily payment. This is why a proper agreement must clearly separate: Operating expenses from Ownership costs and Major repairs. Otherwise, a driver can find himself paying for the vehicle three different ways:
- Through the deposit.
- Through daily payments.
- Through maintenance and repairs.
At that point, he must ask whether the business still makes economic sense.
But Let’s Not Turn Drivers into Saints
There is another side to the story and some drivers are responsible. A vehicle owner may spend a significant amount of money acquiring a car, only for the driver to treat it carelessly. Imagine an owner gives a driver a vehicle and the driver knows that the car belongs to someone else. He drives aggressively and ignores warning lights. He fails to report mechanical problems and overloads the vehicle. Eventually the car develops serious problems. The owner is furious, driver says;
Boss, I didn’t know.
But perhaps he did and ownership may belong to someone else, but responsibility still matters.
The Driver Who Doesn’t Account for Every Trip
There is another problem that vehicle owners sometimes face and that is cash transaction. Suppose a driver makes private trips outside a ride-hailing platform, but the owner expects a certain amount of revenue. The driver doesn’t report every trip. A few cedis here, GH¢50 there, GH¢100 somewhere else and over a month, it can become significant. This destroys trust between the car owner and driver. And when the trust is broken, the owner begins to monitor everything.
Some Owners Also Set Impossible Targets
Now let’s return to the owners. Imagine a vehicle owner sets a daily target that was reasonable two years ago. Then fuel prices increase, traffic becomes worse, competition increases and ride-hailing commissions change. Upon all this, the daily target remains unchanged. The driver now has to work longer to produce the same amount. Which will eventually lead to driving from early morning until late at night. That is where a business model can become dangerous. A target should reflect the economics of the business, and it shouldn’t be based solely on what the owner wants to receive.
The Dangerous Race Against Time
A driver who is behind his target at 8 p.m. has two choices either to go home or accept that he didn’t meet today’s payment or continue driving. If he chooses the second option every day, exhaustion becomes part of the business model. And exhaustion behind the wheel is dangerous. A driver who has been working since dawn may be less alert at night. Reaction times and judgement can suffer. Fatigue can lead to crashes.
When the Owner Takes the Car Back
Repossession is probably one of the most emotionally charged parts of work and pay. For an owner, taking the vehicle back may be necessary to protect an investment. For a driver, it can feel like losing years of his life. Both perspectives can be true, but the driver may genuinely have defaulted. The owner may genuinely have suffered losses, but the process matters. Was there a written agreement?
What If the Driver Has Paid 85%?
This is where contracts need to be much clearer. Imagine an agreement says:
“Failure to make payments will result in termination and repossession.”
That sounds straightforward, but it still leaves questions and what happens to the money already paid? Is there a refund formula? Does the owner deduct depreciation? Does the owner deduct outstanding costs? Does the driver receive credit for the deposit? If the vehicle is sold again, does the previous driver receive anything? These provisions should be written clearly before the first payment is made.
The Importance of Written Agreements
One of the biggest mistakes people make is relying on trust. don’t worry, boss. We are brothers, don’t worry, I’ll take care of you, we don’t need a contract and until there is a problem. Then suddenly: I never said that, that wasn’t the agreement, you were supposed to pay for the repairs. A written agreement protects both parties. It should clearly state:
- Vehicle details.
- Cash value, where relevant.
- Deposit.
- Total agreed payment.
- Daily or weekly payment.
- Payment period.
- Ownership transfer conditions.
- Late-payment consequences.
- Default conditions.
- Repossession provisions.
- Deposit treatment, etc.
- Repair responsibilities.
- Maintenance responsibilities.
- Insurance responsibilities.
- Accident procedures.
- Driver obligations.
- Owner obligations.
- Termination conditions.
- Dispute resolution process
If possible, both parties should obtain appropriate professional/legal advice before entering a significant agreement.
The Bigger Question: Is the Driver Buying the Car or Renting It?
This is perhaps one of the most important questions a driver should understand exactly what he is entering. Is it: A lease? A hire-purchase arrangement? A loan? A rent-to-own agreement? or A vehicle management arrangement? Different structures can have different legal and financial consequences and calling everything “work and pay” does not make the underlying arrangement identical. The name is less important than the actual terms.
The Work-and-Pay Trap
The real danger is not necessarily that work and pay exists, but danger is entering it without understanding the numbers. Someone sees another driver with a nice car and thinks: “I can do this too.” He pays a deposit, takes the car, starts driving, then after a few months, reality arrives.
Fuel is expensive, traffic is exhausting, car needs repairs, daily target is demanding, platform takes its share. food and rent costs money, etc. Then the driver realizes: “I am working all day, but I am not building enough wealth.” That is when the dream can become a trap.
The Difference Between Income and Wealth
This is a lesson every young Ghanaian should learn. Income is not wealth, a driver can make GH¢600 in a day. That doesn’t mean he earned GH¢600, he generated revenue and after expenses, perhaps only GH¢150 remains. And even that may not be pure profit if he needs to reserve money for repairs. Work and pay becomes meaningful when the driver is actually building something.
An asset, savings, skills, business experience, creditworthiness, eventually ownership and if after five years the driver has nothing except exhaustion and debt, something has gone wrong.
The Owner’s Investment Also Deserves Protection
But fairness cannot mean protecting only the driver, vehicle owners also deserve protection and imagine someone invests GH¢150,000 in a vehicle. They hand it to a driver and fail to make payments. The owner still has:
- Loan obligations.
- Insurance.
- Depreciation.
- Repairs.
- Registration costs.
- Lost income.
The owner cannot simply be expected to absorb everything; a fair system must protect both sides. The driver should not be exploited; the owner should not be cheated. Fairness has to run in both directions.
What a Fair Work and Pay Model Should Look Like
A healthy arrangement should answer one fundamental question: Can both sides succeed? The driver should have a realistic opportunity to make income after expenses. The owner should receive a reasonable return on investment, and the vehicle should be properly maintained. The driver should have reasonable working limits, and payment records should be transparent. Default procedures should be clear, and ownership should not be surrounded by hidden surprises. Most importantly, both parties should understand exactly what happens if the relationship ends before the final payment.
Questions Drivers Should Ask Before Paying a Deposit
Before handing over even GH¢1, ask:
- What is the actual value of the vehicle?
- How much is the deposit?
- How much will I pay in total?
- How long will the payment period last?
- Who owns the vehicle before the final payment?
- When exactly does ownership transfer?
- What happens if I miss one payment?
- What happens if I miss several payments?
- Can the vehicle be repossessed?
- If it is repossessed, what happens to my previous payments?
- Is my deposit refundable?
- Who pays for major repairs?
- Who pays for routine servicing?
- What happens if the car is involved in an accident?
- What happens if the car is stolen?
- What happens if I become sick and cannot work?
- Can I terminate the agreement?
If these questions make the other party uncomfortable, that itself should make you uncomfortable.
Questions Owners Should Ask Before Giving Out a Car
Owners should also ask:
- Does the driver have a valid licence?
- Does the driver have sufficient experience?
- Can the driver provide references?
- Does the driver understand the payment structure?
- Does the driver understand who pays for repairs?
- How will daily revenue be monitored?
- How will cash trips be accounted for?
- What happens if the vehicle is damaged?
- What happens if payments are missed?
- How will disputes be resolved?
A good agreement is not one that protects only the owner. It is one that makes the responsibilities of both parties clear.
The Government Has a Role Too
Government cannot simply tell people to become entrepreneurs and then leave them to figure everything out. There must be a regulatory environment that protects legitimate businesses while discouraging exploitation. There should be greater public awareness about:
- Vehicle financing.
- Consumer rights.
- Labour rights.
- Commercial driving regulations.
- Contractual obligations.
- Road safety.
- Financial literacy.
The growth of ride hailing and informal vehicle financing means the traditional employer-employee relationship is changing. Regulation must keep up.
So, Is Work and Pay the New Scam in Ghana?
Maybe the better question is: When does work and pay stop being an opportunity and start becoming exploitation? The answer cannot simply be: “When the driver complains” and it cannot be: “Whenever the owner takes the car back.” We need to look at the contract.
The numbers, conduct of both parties, circumstances of the default, treatment of the deposit, and amount already paid. The repairs made, obligations agreed upon and the law.
A system where a person pays 85% of an agreed amount and loses everything deserves serious questions but a system where a driver takes someone else’s vehicle, refuses to pay and damages the car also deserves serious questions. Both stories can be true.
The Good, the Bad and the Ugly
The Good
Work and pay can give an unemployed or undercapitalized person access to a vehicle and a pathway into entrepreneurship. It can create income, skills, ownership and change lives.
The Bad
Poorly structured agreements can leave drivers struggling with deposits, daily targets, fuel, repairs and uncertain income. Drivers may work extremely long hours simply to meet payments and owners may also face dishonest drivers, poor vehicle care and missed payments.
The Ugly
The situation becomes ugly when trust replaces contracts, desperation replaces negotiation and one side discovers the real terms only after thousands of cedis have already been paid.
It becomes even uglier when a driver who has invested years of work feels that everything has been lost, or when an owner discovers that a supposedly profitable vehicle has been damaged and payments have disappeared.
That is when a business opportunity becomes a battle.
Ghana Must Have the Conversation
The work-and-pay industry is not going away simply because people criticize it. People need jobs, want businesses, cars, independence, and vehicle owners want returns on their investment.
The solution is not necessarily to kill the model but to make it fairer, clearer and more transparent. A driver should know exactly what he is signing up for and carand owner should know exactly what he is giving up.
Both should understand what happens if things go wrong because GH¢50,000, GH¢100,000 or GH¢150,000 is not just money for an ordinary Ghanaian, it can represent years of sacrifice.
MY FINAL THOUGHT
Perhaps the most dangerous sentence in a work-and-pay arrangement is: “Don’t worry. We will sort it out later.” Later is when the problems begin. Put everything into writing, calculate every penny, understand the deposit and ownership conditions.
Understand the repair obligations, default rules, what happens if the vehicle is repossessed and understand what happens to every cedi you have paid because work and pay should be a pathway to ownership not a pathway into years of work with nothing to show for it.
The driver deserves fairness, vehicle owner deserves protection, and Ghanaian workers deserve business arrangements that allow them to build a better future rather than simply work harder to remain in the same place. So before accepting the keys, don’t just ask: How much can I make every day? Ask the question that matter more: After all the work, all the payments, all the fuel, all the repairs and all the risks, what will I actually own at the end?
That is where the real truth about work and pay in Ghana begins.
